

You have ₹6 lakh from a bonus, a maturing FD or the sale of an old plot. Should it go into a mutual fund in one go, or be spread out month by month? People argue about this endlessly, usually with a chart that proves their side. The honest answer is that both methods have a job, and the right one depends on your situation more than on the market.
What each method does
- Lump sum: the whole amount buys units at today’s price. All your money starts working from day one.
- SIP (Systematic Investment Plan): a fixed amount buys units every month, at whatever the price is that month. Your money enters the market gradually.
- STP (Systematic Transfer Plan): a middle path. The lump sum is parked in a liquid or low-duration debt fund, and a fixed amount moves into an equity fund every week or month.
Two markets, two winners
Here is ₹60,000 invested in a fund over six months — either all at once at a price (NAV) of ₹100, or as ₹10,000 a month.
Market A dips, then recovers: the NAV moves 100 → 90 → 80 → 85 → 95 → 110.
- Lump sum: 600 units, worth ₹66,000 at the end.
- SIP: buys more units when the price is low — about 650 units, worth ₹71,500.
Market B rises steadily: the NAV moves 100 → 104 → 108 → 112 → 116 → 120.
- Lump sum: 600 units, worth ₹72,000.
- SIP: about 548 units, worth ₹65,700, because every later instalment paid a higher price.
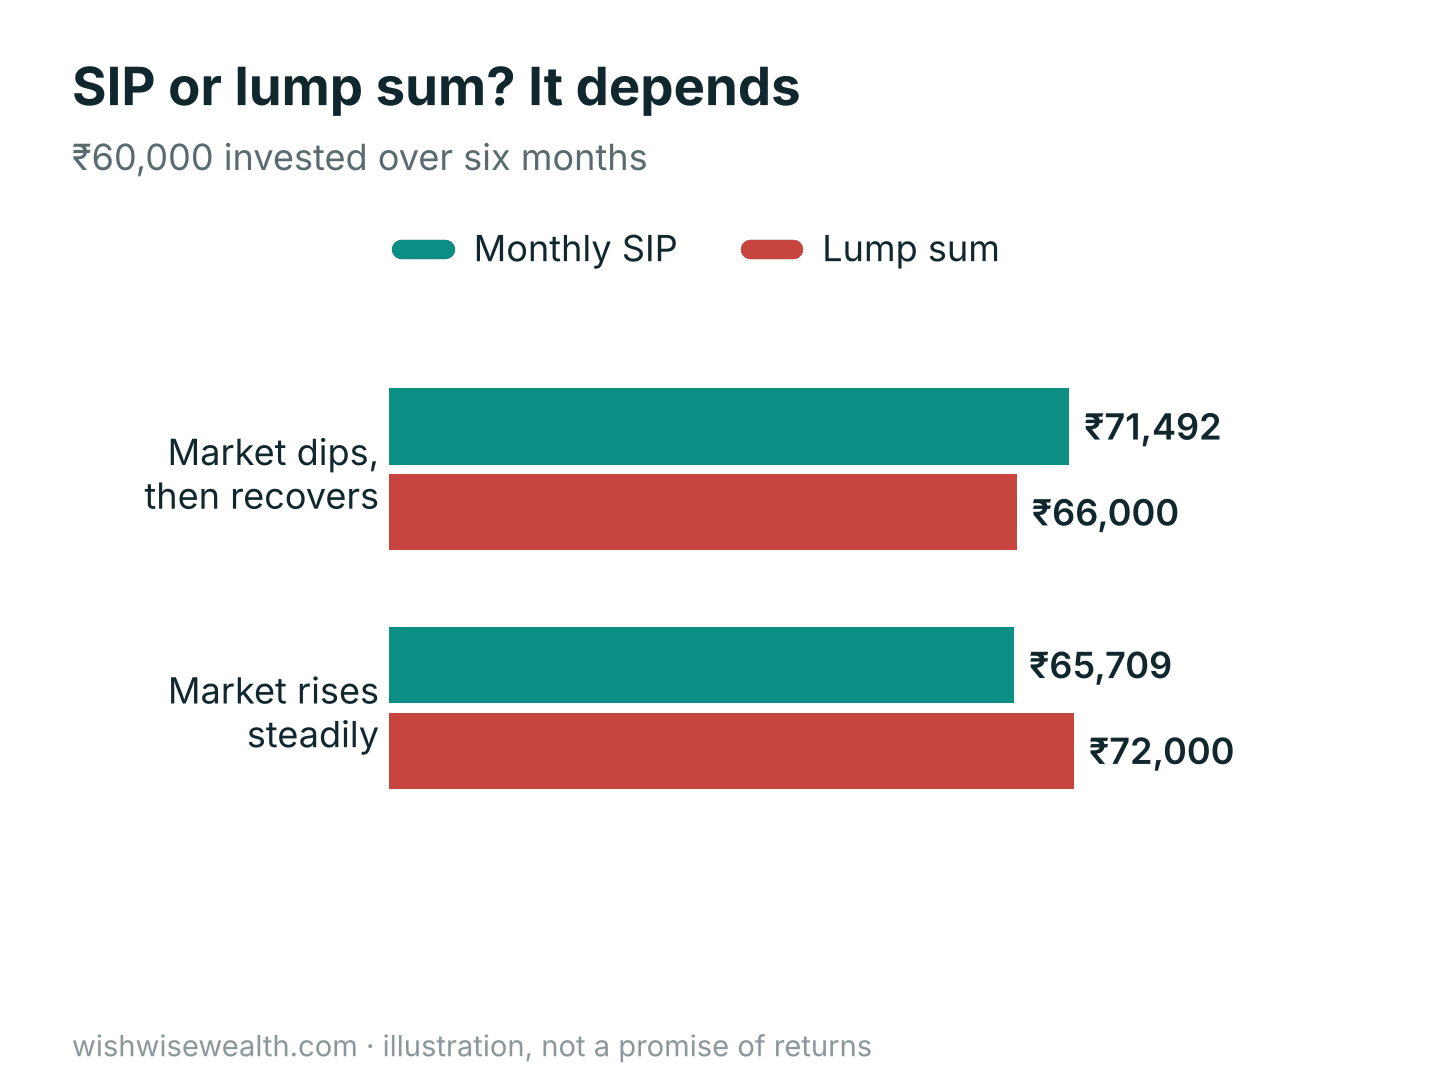
Notice something about Market A: the SIP’s average cost per unit (about ₹92.3) is lower than the average price over the six months (₹93.3). That is rupee-cost averaging — a fixed amount automatically buys more units when prices are low. It is not magic and it does not guarantee a profit, but it does mean a fall is not wasted.
What long-term studies show
Because markets have risen more often than they have fallen over long periods, a lump sum invested in equity has ended ahead of spreading the same money over a year in most historical periods. The catch is in the other periods. If you invest everything and the market falls 25% in the following months, the loss is real, and many people react by selling — turning a temporary fall into a permanent one. A SIP or STP gives up a little expected return in exchange for a much smaller chance of that regret.
A simple way to decide
| Your situation | A sensible approach |
|---|---|
| Money comes from your monthly salary | SIP. There is no lump sum to decide about — invest as you earn. |
| A lump sum that is small compared with your existing investments (say under 10%) | Lump sum is fine. A fall will barely dent the total. |
| A large lump sum, or your first time in equity | STP over 6 to 12 months from a liquid fund. |
| Money needed within three years | Neither into equity. Use a debt fund or a deposit. |
| Money for a hybrid or debt fund | Lump sum. These funds move far less, so averaging adds little. |
How an STP works in practice
Suppose the ₹6 lakh is for a goal fifteen years away. It goes into a liquid fund of the same fund house, where it earns roughly short-term interest rates. A transfer of ₹50,000 moves into the chosen equity fund each month for twelve months. If markets fall during the year, later transfers buy more units; if they rise, at least the earlier transfers caught some of the rise. Either way, you are not left wondering whether you picked the worst possible day.
Two practical points: each transfer is a redemption from the liquid fund, so the small gains there are taxed at your slab rate; and keep the STP period to a year at most — stretching it to three years leaves too much money idle.
Mistakes to avoid
- Waiting for a crash. Holding cash until “the market corrects” often means watching it rise further. If you cannot decide, an STP removes the decision.
- Stopping a SIP when markets fall. That is exactly when a SIP does its best work.
- Treating SIP as a product. A SIP is only a way of paying. What you buy — the fund — decides your risk.
- Choosing by last year’s return. Whether you invest by SIP or lump sum, choose the fund for your goal and time frame.
Frequently asked questions
Can I do both?
Yes, and most families do: a monthly SIP from salary, plus lump sums or STPs whenever a bonus or maturity arrives.
Is a weekly SIP better than monthly?
Over long periods the difference is negligible. Choose the frequency that matches your cash flow.
What day of the month is best for a SIP?
No date is reliably better than another. Pick a date two or three days after your salary credit, so the instalment never bounces.
Not sure which route suits your money? Message us on WhatsApp, or try the lump sum and SIP calculators on our calculators page.
Figures above are illustrations based on assumed rates of return and are not a promise or guarantee of future returns. Mutual fund investments are subject to market risks, read all scheme related documents carefully. WishWiseWealth is an AMFI-registered Mutual Fund Distributor (ARN-188221).