“How do I make ₹1 crore?” is probably the most common money question in India. The honest answer has three parts: how long you have, what return you assume, and whether you will raise your investment over time. Here are the numbers, laid out so you can find your own row.
The monthly SIP you need
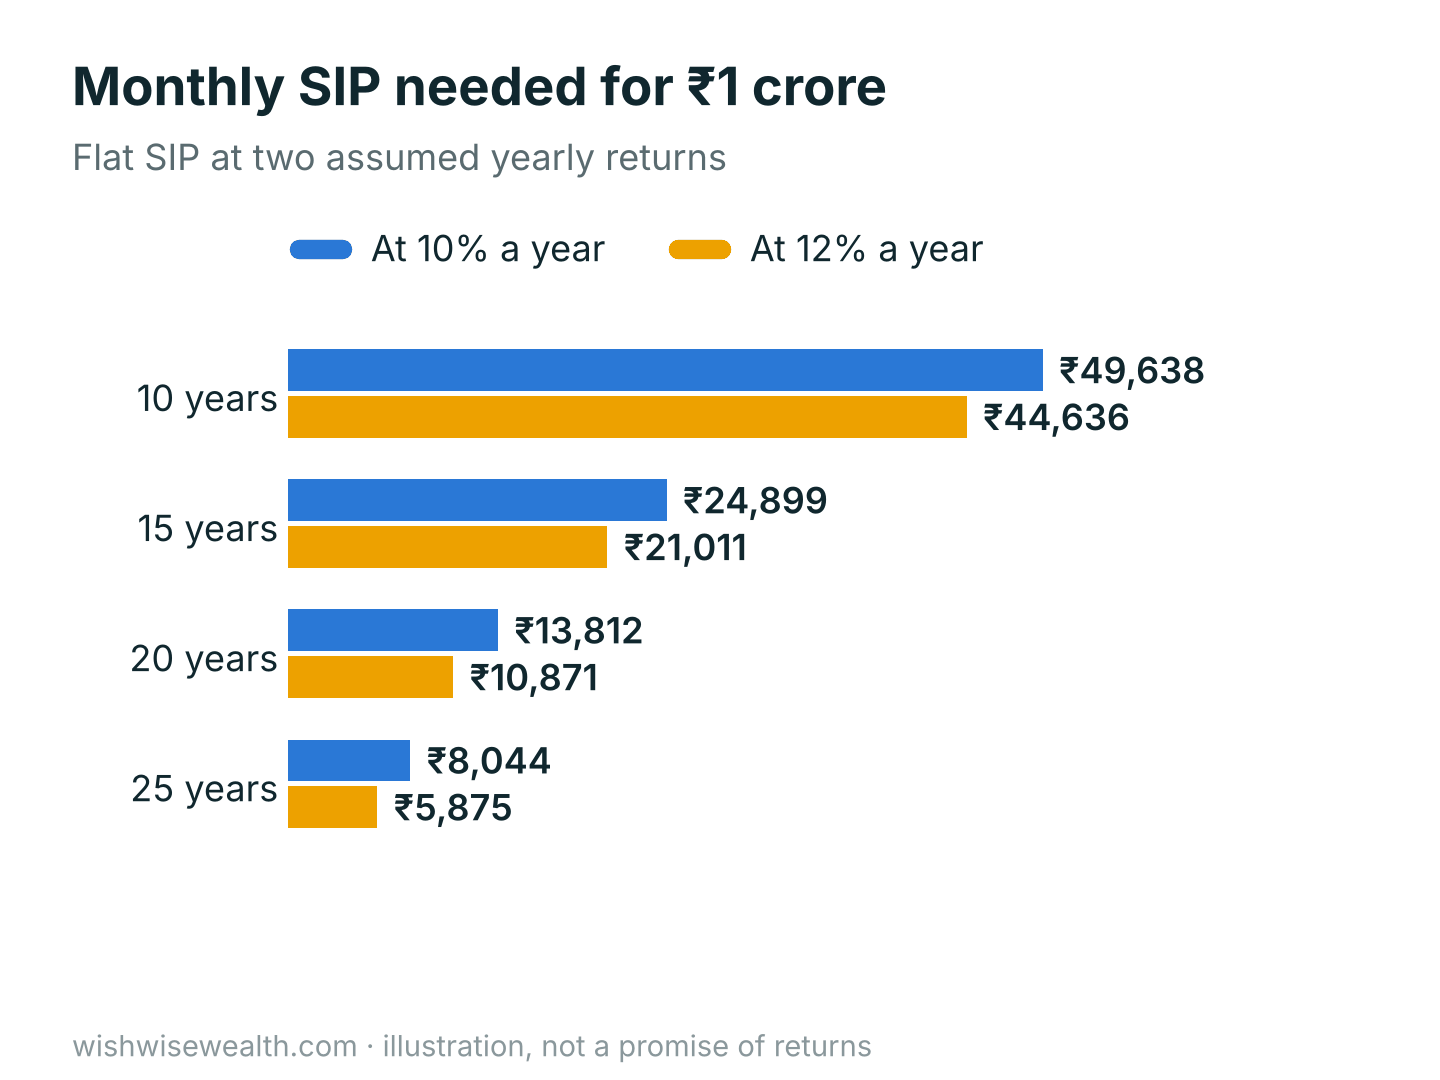
This table shows the flat monthly SIP needed to reach ₹1 crore, at two assumed yearly returns. The last column shows the starting SIP if you raise it by 10% every year.
| Years | At 10% a year | At 12% a year | At 12%, with 10% yearly step-up (starting SIP) |
|---|---|---|---|
| 10 | ₹49,638 | ₹44,636 | ₹30,591 |
| 15 | ₹24,899 | ₹21,011 | ₹12,085 |
| 20 | ₹13,812 | ₹10,871 | ₹5,367 |
| 25 | ₹8,044 | ₹5,875 | ₹2,541 |
Three things stand out:
- Time does most of the work. Going from 10 to 20 years cuts the SIP needed by about three-quarters.
- The assumed return matters more as the horizon lengthens. Over 25 years, the difference between 10% and 12% changes the SIP by over a third. That is why we always plan with the lower figure too.
- A step-up SIP makes big goals reachable early in a career. ₹5,367 a month, raised by 10% each year, reaches ₹1 crore in 20 years at an assumed 12%.
If you have a lump sum instead
A single investment today, left alone at an assumed 12% a year, needs to be:
| Years | Lump sum needed today |
|---|---|
| 10 | about ₹32.2 lakh |
| 15 | about ₹18.3 lakh |
| 20 | about ₹10.4 lakh |
| 25 | about ₹5.9 lakh |
Most families combine both: a monthly SIP from salary, plus bonuses and maturities added as lump sums along the way.
What will ₹1 crore be worth?
This is the question people forget to ask. Prices rise every year. At 6% inflation, ₹1 crore in the future buys what these amounts buy today:
| ₹1 crore received in… | Buys roughly what this buys today |
|---|---|
| 10 years | ₹55.8 lakh |
| 15 years | ₹41.7 lakh |
| 20 years | ₹31.2 lakh |
| 25 years | ₹23.3 lakh |
So ₹1 crore is a milestone, not a finish line. For a real goal — retirement, a child’s education, a house — start from what you need in today’s money, grow it by inflation to the goal year, and then work out the SIP. Our goal calculators do these steps for you.
Making the plan realistic
- Pick a horizon of at least seven years for equity. Shorter goals should use a more conservative mix and a lower assumed return.
- Plan with a conservative return. Use 10% to 11% for diversified equity over long periods rather than the best past decade. If returns are better, you get there early.
- Automate the step-up. Link it to your increment month so it happens without a decision.
- Protect the plan. An emergency fund, health cover and term insurance stop a crisis from breaking the SIP.
- Review yearly, adjust gently. If you are behind, raise the SIP a little or extend the date by a year. Do not chase riskier funds to catch up.
A note on taxes
The figures above are before tax. For equity-oriented funds held over a year, long-term gains above ₹1.25 lakh a year are taxed at 12.5%. Redeeming gradually over a few years, rather than all at once, keeps more of the gain within the yearly exemption. Our tax guide has the details.
Frequently asked questions
Can I reach ₹1 crore in 5 years?
Only with a large monthly amount — roughly ₹1.15 lakh to ₹1.3 lakh a month for returns between 15% and 10% — and a five-year horizon is too short to rely on equity alone. For short horizons, the savings amount matters far more than the return.
Is 12% a realistic return?
It has been achieved by diversified Indian equity over many long periods, but not all of them, and there is no guarantee for the future. That is why every table here also shows a lower assumption.
Want a plan for your own ₹1 crore goal? Message us on WhatsApp with your age and current savings.
Figures above are illustrations based on assumed rates of return and are not a promise or guarantee of future returns. Mutual fund investments are subject to market risks, read all scheme related documents carefully. WishWiseWealth is an AMFI-registered Mutual Fund Distributor (ARN-188221).